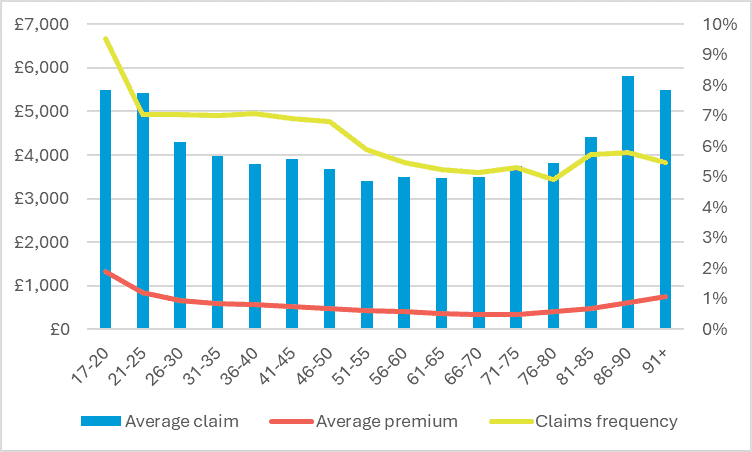
This chart shows the percentage of customers claiming per policy, the average cost of a claim and the average premium for different age groups for private motor insurance in 2023.
The main reason car insurance for young drivers is so expensive is because statistics show that young drivers are far more likely to be involved in accidents than drivers aged 25 and older. Drivers aged 17-24 only make up 7 per cent of UK licence holders and drive fewer miles than the average but are involved in 24 per cent of all fatal collisions.
Young drivers are more at risk and more likely to make a claim, which is why car insurance tends to be more expensive than for older drivers.
We have long campaigned for reforms to help stem rising motor insurance premiums caused by factors such as the current way compensation pay-outs are calculated and a resurgence in whiplash-style claims.
However, insurers cannot solve this problem alone.
More than any other sector of the driving population, young drivers need the Government to act to help them manage their motor insurance bills and we continue to make the case for introducing reforms to personal injury compensation, freezing the rate of Insurance Premium Tax and implementing Graduated Driver Licencing (GDL) to protect both young drivers and those already on the road.
Stay informed about the factors driving recent increases in insurance premiums. Our comprehensive FAQ addresses key issues such as the rise in motor insurance costs, the impact of regulatory reforms, and the various factors insurers consider when assessing risk.
Young drivers remain a major danger on the road, to themselves, their passengers and other road users. Young drivers are grossly overrepresented in the official accident figures and each statistic represents a tragic waste of life that could be prevented.
We have long campaigned for safer roads. We have consistently argued that unless radical reforms are made, the poor safety record of young drivers will continue. If the number of crashes involving young drivers decreases, the financial risk they pose to an insurer will decrease and insurance premiums for young drivers will follow.
Crashes involving young drivers are generally the result of one or more of the following:
Graduated driver licensing (GDL) is designed to delay full licence issue, allowing beginners to obtain their initial driving experience under lower risk conditions. It is divided into three stages: a minimum supervised learning period, an intermediate licence period that places restrictions on the newly qualified driver, and the acquisition of a full, unrestricted, driving licence available after completion of the first two stages.
The current UK licensing system allows a young person to drive unaccompanied and with no restrictions as soon as they pass their practical driving test unlike with a motorbike where they have graduated licensing. It is therefore unsurprising that many young people try to pass it in as little time as possible, many taking just a few months to learn the skills required to pass the test. The result is that inadequate emphasis is placed on the benefits of gaining road experience and, subsequently, young drivers can have little experience of driving in different road and traffic conditions. It is unsurprising that these drivers with the least experience subsequently go on to have the highest crash rates when fully licensed.
There are a large number of different rating factors used in setting the price for motor insurance, including who is driving. Age can materially influence both the likelihood of policyholders making a claim and the cost of such claims when they occur, with average premiums for motorists closely linked to the average claim for all ages.